Over 25s Van
Insurance
Award Winning UK call-centre support 🇬🇧
Compare & Save £114 on average 🏷️




Free 10%OFF
TradePoint
Discount Card

Published: | Last updated:
| Last reviewed:
🏠 Home > 👷 Type > 🚐 Over 25s Van Insurance
Over 25s Van Insurance
Drivers aged 25 and above often benefit from lower premiums thanks to driving experience and lower claim statistics. VanCompare.com makes it easy to compare policies and maximise your savings.
GET QUOTES Get a quote in 3 mins
 Expert UK team


What is Over 25s Van Insurance?
It’s van insurance specifically priced for drivers over 25, reflecting reduced risk and better accident records — without compromising on cover.
GET QUOTES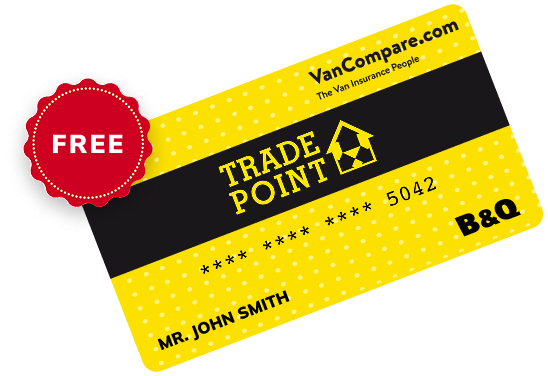 FREE 10% OFF
Tradepoint Discount Card on purchase.
Why Do You Need It?
Even though drivers over 25 benefit from lower premiums, the right policy still matters. Turning 25 often unlocks access to more insurers, better pricing, and wider cover options — but accuracy around how your van is used remains essential for compliance and claims validity.
GET QUOTESWhy Premiums Often Drop at 25
-
 More driving experience and time held on full licence
-
Cleaner driving history and early NCB growth
-
Broader insurer competition at 25+
-
Lower claims frequency compared with under-25s
Types of Over 25s Van Insurance

01
Comprehensive (Fully Comp)
Includes damage to your own van and personal-injury cover, even in at-fault incidents.
03
Third Party Only (TPO)
Covers damage or injury you cause to others — the legal minimum level of protection.
02
Third Party, Fire & Theft (TPFT)
Adds protection if your van is stolen or damaged by fire.
04
Optional Extras
Enhance your policy with add-ons that offer practical benefits.
Your Cover, Explained
Strong Base Protection
Meets legal minimums while covering liability to others and your vehicle.

Protect Your NCB
Safeguards your growing discount from single-incident setbacks.

Usage Flexibility
Choose social, business, or courier classifications as required.
Confidence Features
Breakdown and courtesy van options reduce downtime if things go wrong.
How to Lower Your Over
25 Premiums
-
 Keep annual mileage realistic and low.
-
Avoid points on your licence .
-
Use secure overnight parking.
-
Choose vans in lower insurance groups.
-
Maintain and protect your no-claims bonus.
-
Consult an FCA-regulated broker to ensure your policy remains competitive.
Over 25 Van Insurance: FAQs & Key Insights
1. What is Over 25 Van Insurance?
Over 25 van insurance is designed for drivers aged 25 and above who typically present a lower risk than younger drivers. Turning 25 does not automatically reduce your premium, but many drivers see improved pricing because of the risk and market factors below.
2. Why premiums often improve at 25
- Licence tenure: many 25-year-olds have held a full UK licence for longer, signalling more experience.
- Clean driving history: there is more time to build claim-free years.
- No-claims bonus (NCB): by this age many drivers have accumulated several years of NCB.
- Broader insurer panel: more underwriters are willing to quote at 25+, which increases competition and can bring prices down.
- Fewer product restrictions: some schemes that are closed to under-25s open up at 25, including lower compulsory excesses or wider cover options.
Pricing always depends on multiple factors, including vehicle, postcode, occupation, mileage and claims. These are general patterns, not guarantees.
3. NCB and underwriting considerations
Many drivers aged 25 and over will already have been policyholders for several years and will have
begun building
their NCB. Those who have had to make claims may have seen this reduced, as many insurers only allow
NCB protection
once four or more years have been accumulated.
At this stage, a wider range of specialist underwriters may also become available. Many of these
providers only
begin quoting from age 23 upwards and often target specific risk profiles — such as drivers with low
or interrupted
NCB, multiple claims, or past convictions. For drivers in these categories, reaching 25 can open up
new markets and
policy options that were previously unavailable.
4. Cover levels explained
- Third Party Only – meets the legal minimum. No cover for your own van.
- Third Party, Fire and Theft (TPFT) – adds theft and fire cover for your van
- Comprehensive – includes accidental damage to your own van as well as full third-party protection. On some vehicles Comprehensive can be competitively priced versus TPFT.
5. Useful add-ons for over-25 drivers
- Windscreen and glass cover
- Courtesy van while yours is off the road
- UK and European breakdown cover
- Legal expenses cover
- Tools or goods in transit cover for business users
- Protected no-claims discount, where eligible
6. How to keep premiums low at 25+
- Choose a van in a lower insurance group and avoid unnecessary modifications.
- Keep annual mileage realistic and as low as practical.
- Park in secure locations overnight and consider approved alarms, immobilisers or trackers.
- Maintain a clean licence and claims record to continue building NCB.
- Consider named-driver policies rather than any-driver if only a few people use the van.
7. Common misconceptions
- “Age alone makes it cheap.” Age is one factor. Pricing also reflects claims history, NCB, vehicle, usage and location.
- “Non-fault claims do not matter.” Even non-fault or notification-only incidents can influence pricing.
- “Business use is automatic.” You must disclose the correct class of use. Carrying tools, visiting multiple sites or doing deliveries usually requires business classifications such as carriage of own goods or hire and reward.
8. Compliance note
Insurers, under FCA oversight, expect accurate disclosure of driver details and vehicle use. Mis-stating class of use, omitting claims or not declaring modifications can lead to cover being declined or a claim being refused.
9. Quick comparison: 21 vs 25 vs 30+ (qualitative)
- 21+: supply of quoting insurers improves versus under-21, early NCB building phase.
- 25+: broader panel access, specialist markets open, more cover options.
- 30+: risk often stabilises further for many profiles, subject to driving record and vehicle type.
10. Is van insurance always cheaper at 25?
Not always. Many drivers see improved prices at 25 due to experience and increased insurer competition, but your premium still depends on your claims record, NCB, van, postcode and usage.
11. Can I get business cover at 25?
Yes. Most insurers will consider business use at 25+, including carriage of own goods. Courier or hire and reward cover may have additional criteria.
12. Will a non-fault claim affect my price at 25?
It can. Insurers consider the full incident history, including non-fault and notification-only claims, when assessing future risk.
13. Does protected NCB stop prices rising after a claim?
Protected NCB can preserve your discount step, but base rates may still change after a claim. It protects the discount, not the underlying premium.
Why Use VanCompare.com
We compare leading UK insurers to find the best-value van insurance for drivers aged 25 and above — balancing cost, cover, and confidence.
See how VanCompare works GET
QUOTES
Our Benefits Include:
-
10% B&Q TradePoint Discount Card
-
Award-Winning App
-
4.5★ Rating (11,000+ reviews)
-
Multi-Award Winning Comparison Site
-
UK-Based Support Team


Compare Over 25s Van
Insurance Quotes
Get tailored cover for drivers over 25s — compare quotes now at VanCompare.com.
Get Quotes